Hear from our editors: The best low-interest credit cards of October 2026
Updated September 30, 2026
This date may not reflect recent changes in individual terms.
Editorial Note: Intuit Credit Karma receives compensation from third-party advertisers, but that doesn’t affect our editors’ opinions. Our third-party advertisers don’t review, approve or endorse our editorial content. Information about financial products not offered on Credit Karma is collected independently. Our content is accurate to the best of our knowledge when posted.
Written by: Eric Freeman
Edited by: Claire Diver, Senior Editor, Credit Cards
The best low-interest credit cards can help you finance expensive purchases, pay off existing debt or just achieve valuable peace of mind. Depending on your needs, they can be valuable tools as you manage your finances and ongoing costs.
Read on for our picks for the best low-interest cards, which offer 0% intro APRs and other useful features.
- Wells Fargo Reflect® Card: Best for a long intro period
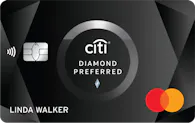
- Citi® Diamond Preferred® Card: Best for balance transfers
- Chase Freedom Flex®: Best for bonus categories
- U.S. Bank Shield™ Visa® Card: Best for travel
Wells Fargo Reflect® Card: Best for a long intro period
Here’s why: This card gives you a 0% intro APR for 21 months on purchases and balance transfers. Balance transfers must be made within 120 days of account opening, and the balance transfer fee will cost you 5% (minimum $5).
After your intro periods are over, the APR for both purchases and balance transfers rises to a variable 17.74%, 24.24%, 28.49%.
Read more about the Wells Fargo Reflect® Card.
Citi® Diamond Preferred® Card: Best for balance transfers
Here’s why: The Citi® Diamond Preferred® Card offers a lengthy 0% intro APR for 21 months on balance transfers completed within four months of account opening. The card has a balance transfer fee: Intro fee 3% of each transfer ($5 minimum) completed within the first 4 months of account opening. After that, 5% of each transfer ($5 minimum). After the intro period is over, the regular variable APR for balance transfers rises to 16.74% - 27.49%.
The card also offers 0% intro APR on purchases for the first 12 months after account opening (after the intro period, the regular purchase APR rises to a variable 16.74% - 27.49%). But we recommend using this card to pay off balances over a long period of time, rather than using it to make new purchases.
Read more about the Citi® Diamond Preferred® Card.
Chase Freedom Flex®: Best for bonus categories
Here’s why: You can earn high cash back rates in numerous categories and save on interest with the intro APR offers.
This card offers 5% back on up to $1,500 spent on bonus categories that rotate every quarter. You must activate your bonus categories before you can earn the 5% rate. After you reach the spending cap each quarter, you’ll earn 1% back.
But this card stands out for its additional bonus categories. You’ll also earn 5% back on travel purchased through Chase, 3% back at restaurants (including takeout and delivery) and drugstore purchases, and 1% back on all other purchases.
The card offers an intro 0% APR on purchases and balance transfers for the first 15 months after your account opens. There’s also a balance transfer fee: Either $5 or 3% of the amount of each transfer, whichever is greater in the first 60 days. 5% (minimum $5) thereafter. After the intro period, the variable APR for purchases and balance transfers rises to 18.24% - 27.74%.
Learn more about Chase Freedom Flex®.
U.S. Bank Shield™ Visa® Card: Best for travel
Here’s why: You can save on interest while earning cash back for qualifying travel purchases with the U.S. Bank Shield™ Visa® Card.
The card offers a 0% intro APR for 21 billing cycles on purchases. After the intro period ends, the regular variable purchase APR rises to 17.24% - 28.24%.
With this card, you’ll earn 4% cash back on prepaid air, hotel and car reservations booked through U.S. Bank’s Travel center.
The card also has a decent balance transfer offer: 0% intro APR on balance transfers made within 60 days of account opening for the first 21 billing cycles. There’s a balance transfer fee: Either 5% of the amount of each transfer or $5 minimum, whichever is greater. After the intro period ends, there’s a regular variable APR of 17.24% - 28.24% on balance transfers.
If you plan to use the card for a balance transfer, we’d recommend waiting until the balance is paid off before making new purchases with the card.
How we picked the best low-interest credit cards
We chose the best low-interest credit cards with a focus on delivering options that either allow you to take maximum advantage of an intro 0% APR or balance a solid intro offer with ongoing rewards value.
All of our selections offer a 0% intro APR on both purchases and balance transfers, and we only selected cards with intro periods that lasted for at least 15 months for both types of APR. With more than a year to manage your credit card balances, these picks are useful tools for keeping track of your finances.
While those most concerned with paying off existing debt can find other cards with longer balance transfer intro periods, we decided not to include those that feature shorter purchase APR intro periods. If you’re looking for more options, consider our picks for the best balance transfer cards and the best 0% APR cards.
We also made sure every card on our list doesn’t charge an annual fee — you probably don’t want to pay that upfront cost when you’re already thinking about how to handle interest payments.
Last, we consciously chose not to select cards that offer the potential to receive an especially low ongoing purchase APR. While a low ongoing APR can be a terrific feature in a credit card, there’s no guarantee the issuer will approve you for the lowest possible APR, even if you have excellent credit.
In the end, we considered it best not to suggest you’re likely to end up on the lower end of a card’s APR range when we don’t know exactly how each issuer will determine your interest rate.
When should you get a low-interest credit card?
There are three main reasons to get a low-interest credit card — to pay off existing debt, to avoid going into debt when making a big purchase, and to gain valuable peace of mind.
Paying off existing debt
A low-interest credit card with a 0% intro APR offer for balance transfers can help you pay off your high-interest debt over the introductory period.
If you transfer your balances from one or several credit cards to the new card with a 0% interest rate, you’ll be able to take more time to pay off your balances without worrying about new interest payments. But balance transfers come with plenty of risks, so make sure to do your research before you get started.
Making a big purchase
If you’re planning to make a big purchase with a credit card, like a major appliance, then a low-interest card with a 0% APR offer on purchases can help you manage that cost over an extended period.
When you make a purchase during the intro period, that balance won’t be charged interest until your 0% purchase APR ends. But keep in mind that you can lose an intro offer if you miss payments, and that making new purchases while also paying off balance transfer debt can lead to complications and even greater interest payments than you might’ve had before you got your new card.
Looking for peace of mind
Sometimes you don’t need a pressing reason to get a low-interest credit card. If you’ve had trouble with interest payments in the past or even just don’t want to worry, these cards can help you stay relaxed.
How do 0% APR offers work?
A 0% APR offer allows you to make new purchases or transfer balances without paying interest during the introductory period.
For instance, if a card offers a 0% APR on purchases for 15 months, then any new purchases you make in that time won’t accrue interest until the offer ends. If the card also offers a 0% APR on balance transfers for those 15 months, then you can transfer balances from other cards to your new card (usually while paying a balance transfer fee) and pay the combined balance without interest until the offer period ends.
These offers can be useful ways to manage debt, but they’re also quite complicated and full of risks. You might end up paying more interest than planned if you can’t pay off your balances by the end of your intro periods. And mismatched offers — where the purchase APR and balance transfer APR last for different lengths of time — could see you stuck accruing interest on your new purchases until you pay off your full transferred balance, even if you still have a 0% APR on balance transfers.
We strongly recommend reading the terms and conditions before applying for any credit card, but it’s especially important for a card with a 0% offer. These cards are tools to help you with your finances, not shortcuts to managing debt.
What are good ways to reduce interest costs?
If you find yourself making large interest payments, there are several ways to help your situation. A 0% intro APR offer on balance transfers can help you get out of debt, and a 0% intro APR offer on purchases can help you pay off balances over time if you’ve had issues with interest in the past.
If you don’t want a new credit card, you could try to lower your credit card interest rate. This method can be challenging because your credit card company has to agree to do it. But if your credit is in good shape and you have a history of on-time payments, it may be a possibility.
You may also consider consolidating credit card debt with a personal loan. Depending on your circumstances, this option might make getting out of debt a more manageable process.